Leaving Is the Half You Forgot
The standard nomad domicile plan goes like this. Pick South Dakota or Florida or Texas. Sign up with a mail-forwarding service. Fly in for a weekend, get the driver’s license, register to vote, and leave. Congratulations: you’re a resident of a state with no income tax, and you never have to go back.
That plan does half a job, and the easy half. It gives you paper in a new state. It does nothing about the old one, and for income tax the old one is the one that matters, because the old one has a tax department and a claim on you.
North Carolina says so in its definition of “resident,” G.S. 105-153.3(15):
A resident who removes from the State during a taxable year is considered a resident until he has both established a definite domicile elsewhere and abandoned any domicile in this State.
Both. The state you left doesn’t care that South Dakota was happy to have you. It cares whether you left, and it gets to decide that question under its own rules, with the burden of proof, in North Carolina and in every state I’ve looked at, on the person claiming to have gone. The details differ from state to state. The principle, that your old domicile lasts until you’ve replaced it, doesn’t, and the states with real money at stake have an audit staff to go with it.
I moved from North Carolina to Florida in December 2014. I’m a retired lawyer, and I spent the following year doing something most people who make this move never do: I lived in the new state, and I kept the record of living there in a form that would hold up if North Carolina came looking. It never did. That’s the outcome I was paying for.
What a hostile reading looks like
North Carolina isn’t famous for chasing former residents the way New York and California are. It has the tools anyway, and the year I moved, it was using them on a couple from Raleigh.
Steve and Sandra Fowler had lived in North Carolina all their lives. On January 19, 2006, they signed the agreement to sell their grading business for $106 million. On January 20 they flew to Naples, Florida on a chartered plane, in the court’s words, “for the purpose of taking ‘official action’ to evidence their change of domicile.” The sale closed February 3. By March they had Florida driver’s licenses, Florida voter registrations, and a Declaration of Domicile on file with the county clerk. They also kept their Raleigh house, kept insuring it as their primary residence, and that year Mr. Fowler spent 162 days in North Carolina and 51 in Florida. In 2007 it was 168 and 27.
The Department of Revenue treated them as North Carolina residents for 2006 and 2007, the years the sale proceeds landed, and issued its final determinations in October 2011, more than five years after the move. An administrative law judge at the state’s Office of Administrative Hearings sided with the Fowlers at the end of 2012. The Department rejected that decision in its own final ruling. The Fowlers won in Business Court and won again in the Court of Appeals in August 2015, which held they “were not required to remove all of their possessions and sever all ties with North Carolina to effect a change in domicile.”
They won. It took nine and a half years from the flight to Naples to the last opinion, and they won on the strength of a large, expensive record about intent, against a fact pattern where they were in the old state three to six times as often as the new one. The paper was complete. The living wasn’t. That gap is what the Department spent years arguing about, starting long after the Fowlers thought the question was settled.
My tax lawyer in North Carolina knew the Fowler facts well, and the plan we built was designed to never produce a fact pattern like theirs.
The routine events of life
The Department publishes the factors it uses to decide where you live. The list is long, and the sentence that introduces it is the one to memorize. An individual’s legal residence, the Department of Revenue’s Personal Taxes Bulletin says, “is reflected more by the routine events of life rather than events such as voting or obtaining a driver’s license which may occur every four to eight years.”
The factors include the address on your federal return, your insurance policies, and your credit card statements. Where your doctors, dentists, and pharmacists are. Church, club, and lodge memberships. Where you vote and where you actually cast the ballot. Where your pets live. And a category the state describes as “activities for everyday ‘hometown’ living, such as grocery shopping, haircuts, video rentals, dry cleaning, fueling vehicles, and automated banking transactions.”
Read that list as a nomad with a mail drop and a weekend driver’s license and you’ll see the problem. You have the two items the state just told you it finds least revealing, and not much else. Read it as a lawyer preparing for a fight you hope never comes, and it’s a to-do list.
The year in Miami Beach
I moved in December 2014, on purpose. Florida has no income tax return to file, so the document that recorded the move was North Carolina’s: a 2014 part-year resident return with a December date on it. North Carolina’s part-year rules ask for the day your domicile moved, and I wanted that day to be one I could prove, not one I’d have to argue about later. One month put the date on paper. The year that followed is what I’d have pointed to if anyone had asked whether I meant it.
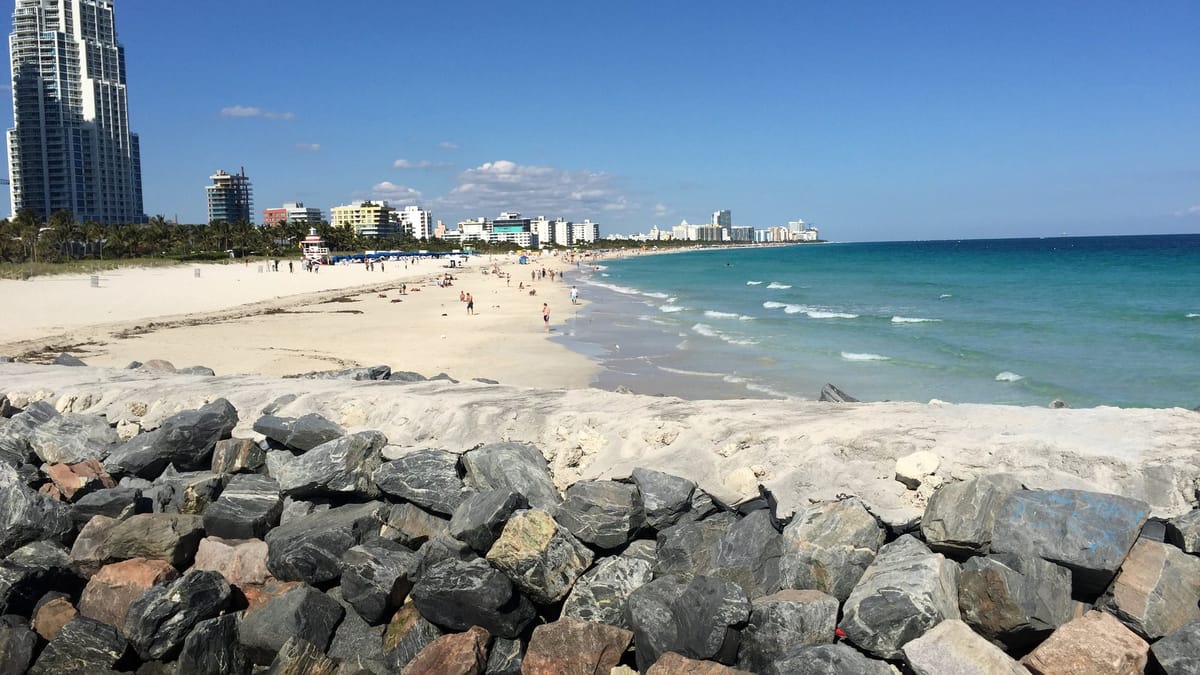
Then I rented an apartment in Miami Beach and lived in it for all of 2015.
One of the Florida lawyers I consulted said something I’ve repeated many times since. Everybody who’s trying to become a Florida resident buys a condo, he said, and then doesn’t live in it. They rent it out. Nobody rents an apartment in order to become a resident. Renting is what people do when they actually live somewhere. He was describing the Fowlers before I’d read the case.
I did the paper. Declaration of Domicile filed with the clerk. Florida driver’s license. Voter registration, and then I voted. Florida will and estate plan, executed under Florida law, because Florida limits who can serve as a personal representative from out of state, and because a will redone in the new state is a dated statement of where you say you live. Then I did the part that isn’t paper. I found a doctor, a dentist, an accountant. I went to appointments. I rented a desk at a co-working space. I went to the public library a couple of times a week. I bought groceries and coffee and kept the receipts, every one of them, scanned, for the whole year.
Nobody wants to read a year of coffee receipts. That’s the point. A year of Miami Beach grocery receipts is hard to fake and harder to explain away, and it answers the first question an auditor asks, which is where were you, without an argument. Intent is the second question, and a year of daily life is the best evidence of intent there is.
I wasn’t in the apartment every day of that year. We took trips, some of them out of the country. The apartment was where I came back to, which is what the law means by a domicile: the place you intend to return to. When the lease ran out I packed two bags and left on a longer trip, and the trips have been getting longer for eleven years. Florida is still the place I return to, and the only place I’d call home.
The nomad’s problem, and the expat’s
That last sentence is easy to write and harder to defend, and it’s where a nomad’s situation gets awkward.
A domicile is the place you intend to return to, and everyone has exactly one, whether or not they’ve been there lately. Lisa and I have no home anywhere in the ordinary sense; we sleep in a different city most weeks. But a domicile isn’t a home, and mine is Florida, where I left it. It stays Florida until I acquire another one, which a life in hotels never does. If I had gone straight from Raleigh to the road in 2014, with no Florida year in between, the same rule would have worked against me. North Carolina requires a “definite domicile elsewhere” before the old one is gone, and a backpack isn’t a domicile. I’d have been a North Carolina resident in every country I visited, and in any year I hadn’t filed a North Carolina return, the Department could have said so whenever it liked.
An expat is in a different position. An expat moves somewhere and settles there, and the somewhere doesn’t have to be a U.S. state. A Portuguese residence permit, a Lisbon lease, and a Portuguese tax return are the raw material of a definite domicile elsewhere, and a state auditor knows what to do with them. The expat’s old state can still argue the move was temporary, but the expat has an answer.
The nomad has to manufacture the answer, because the life itself won’t produce one. That is what the year in Miami Beach was: a domicile, built on purpose, so that I’d have one to point to. I’ve written elsewhere that I think a permanent home base is a trap, and I still think so. But I suspect this problem is one of the reasons people reach for a base without being able to say why. Something in them knows that a person who lives nowhere is, in the eyes of the state he came from, a person who never left.
The side that gets forgotten
Establishing Florida was the easy half. Abandoning North Carolina was the half the plan was actually about, and it was harder for me than for most people, because I was the only one in the family who moved.
Our youngest was finishing high school in Raleigh. Lisa stayed in our rented apartment there until graduation in June 2015. And the business I’d built was a law firm in North Carolina, which wasn’t going anywhere; I didn’t sell it until 2018.
Each of those is a fact the Department could have used. The statute says “the fact of marriage does not raise any presumption as to domicile or residence,” which is true and not much comfort, because the location of your spouse and children is on the factor list of every state I’ve looked at, and auditors start from the assumption that married people live together. So we treated Lisa’s six months in Raleigh the way we treated everything else: as a fact to be explained by paper dated before anyone asked. In early 2015, on trips down while our kid finished school, she got her Florida license and registered to vote in Florida. The paper didn’t make the Raleigh apartment temporary; her intent did. The paper is how you show intent before anyone asks, and it turned the apartment from “the family home” into “where a Florida-domiciled couple waited for a graduation.” Our returns that year were joint, with a Florida address. In June she left.
The firm was the bigger exposure, and the answer was structural. I was a W-2 employee, working from Florida and then from wherever we happened to be. For a nonresident, North Carolina taxes wages only to the extent the work is done in North Carolina, and the Department’s own withholding bulletin says an employer in the state needn’t withhold for a nonresident who performs no services there. The firm’s corporation paid out what it earned as compensation, so there was no profit sitting in a North Carolina entity for the state to reach as mine. Every day of work performed inside the state would have been a day of North Carolina wages and a reason to look harder at the rest, so there were no such days. When the firm sold in 2018, what I sold was my shares in the corporation, with no consulting agreement and no noncompete attached, and the gain on shares is taxed where the seller is domiciled, which by then had been Florida for four years. The 2018 North Carolina return showed zero like the others. Between December 2014 and the sale I went back to North Carolina once, for the graduation and to close out the apartment. I did no work while I was there, and I did not walk into my own firm.
The rest was subtraction. We didn’t own a house or a car in North Carolina by then, which helped. Every account with a North Carolina address got a Florida one. I stopped seeing North Carolina doctors. I kept one North Carolina bank account and never used it, and if you’re wondering whether that would have come up in an audit, yes, it would have, and the answer would have been the twelve months of zero activity.
The return that showed nothing
Nobody outside a tax practice thinks to do this part.
North Carolina’s statute of limitations on assessing tax is three years from the later of the due date or the date you filed. But G.S. 105-241.8(b)(2) says that if “the taxpayer did not file a return,” there is no statute of limitations at all; the Department “may propose an assessment of tax due from a taxpayer at any time.” No return, no clock. Think about what that means for the nomad who simply stops filing in the old state. If he really left, he owed nothing and no return was required. But the whole dispute is whether he really left. If the state decides in 2031 that he didn’t, then a return was required for every year since, none was filed, and there is no year the state can’t reach.
So I kept filing North Carolina returns. Nonresident returns, jointly signed, every year from 2015 through 2021, each one reporting our full federal income and allocating none of it to North Carolina. Simple returns; the North Carolina column was zeros. Each one told the Department where I said I lived, showed it exactly what I was and wasn’t paying tax on, and started a three-year clock on the year it covered. Each clock ran out. The last of them has now expired, and North Carolina never asked a single question.
That is the whole payoff of the strategy, and it’s the opposite of dramatic. The record was built to survive a hostile reading and was never read. Filing the zeros is what let the exposure end. Not filing them would have left the question open for the rest of my life.
The mailbox is not the address
Nomads get this part wrong constantly, and plenty of what’s written about nomad life describes a mail-forwarding service as if it were doing more than it does.
A commercial mail-forwarding service does one thing: it receives mail and scans it. That’s a convenience, and we use one. It is not a residence, and it settles nothing about where you live. Every question that matters, the license, the voter roll, the bank accounts, the estate documents, the answer to “where do you live,” resolves around a physical address: a Florida home we’re authorized to occupy, and where we live when we’re in the state. Florida’s driver license rules require two documents showing a Florida residential address, and if you don’t have documents in your own name, the person you live with signs a Certification of Address, form HSMV 71120, swearing that you reside at their home, and attaches their own lease or deed plus a second document in their name. Banks run address-verification software that flags the big forwarding services. So do Medigap insurers, which I covered in The Medicare Stack. A tax auditor in your old state who sees a mailbox number where your home should be has found the first exhibit.
South Dakota will let you do it the other way. Its residency affidavit for full-time travelers accepts a personal mailbox at a mail-forwarding service as your address, backed by a receipt for one night at a South Dakota campground or hotel within the past year and your sworn statement that you have no other residence. Texas accommodates the same arrangement through a different form. That is a real convenience, and it reads like a confession. A driver’s license issued on the strength of a mailbox and one night in a motel says, in the plainest possible terms, that you don’t have a home in the new state. Your old state’s auditor will read it that way, and North Carolina’s factor list, which starts with where you actually live and ends with where you buy groceries, gives him every reason to.
The states that actually run the machine
I’ve quoted North Carolina because North Carolina is where I left from. Don’t take that as a reason to relax if you’re leaving from somewhere else. The people who run state tax departments belong to the Federation of Tax Administrators, whose members are the tax agencies of all fifty states, and they hold an annual meeting. So do the legislators who write the tax codes. I’ve never heard of a session at either on collecting less from people who move away. If your state has an income tax, expect to find rules that look a lot like the ones above, and a department that has thought harder about your departure than you have.
North Carolina had the tools and, in my case, left them in the drawer. Some states don’t.
New York requires “clear and convincing” evidence that you changed domicile, and it runs the most developed residency-audit operation in the country: roughly 3,000 nonresident audits a year between 2010 and 2017, collecting about $1 billion. The auditors work from five primary factors, home, business, time, family, and what the guidelines call items “near and dear,” which is where the famous question comes from: where do you keep your teddy bear? There is a second route to being taxed as a New Yorker with no domicile argument at all: keep a permanent place of abode there and spend more than 183 days in the state, with any part of a day counting as a day, except for passing through and hospital stays. In October 2025, in Matter of Hoff, the Tax Appeals Tribunal ruled against a couple who had owned a Florida home since 2014 and had a Florida Declaration of Domicile on file since 2018, because they kept their large New York house, spent more days in New York than in Florida, and kept their business ties and club memberships. Years of Florida paper, and they lost on the living.
California defines a resident as anyone in the state “for other than a temporary or transitory purpose,” plus anyone domiciled there who is away for a temporary or transitory purpose. Spend more than nine months of a year in California and you’re presumed a resident. The Franchise Tax Board’s test is “closest connections,” and its published factor list is the North Carolina list with more items: spouse and children, principal residence, license, vehicles, voter registration, banks, doctors, dentists, accountants, attorneys, church, clubs, real property. If you never file a California return for a year California thinks you owed one, R&TC 19087 lets the Board assess “at any time.” And if California still considers you a resident, it taxes your worldwide income without honoring the federal foreign earned income exclusion, a detail that has surprised more than one nomad who thought Sacramento was behind him.
Minnesota’s regulation lists two dozen factors, including “address where mail is received” and “statements made to an insurance company, concerning the person’s residence.” Practitioners there describe the Department subpoenaing credit card and bank statements and cell phone location data. Massachusetts taxes you as a resident if you’re domiciled there or keep a permanent place of abode and spend more than 183 days in the state, any part of a day counting, and its Department of Revenue audits nonresidency claims as a matter of routine. Connecticut, New Jersey, and Virginia each run a 183-day test of their own, with the burden on you. Illinois presumes that last year’s resident is still a resident this year if he spent more days in Illinois than in any other state, and requires clear and convincing evidence to rebut it.
These rules share a shape. The state you left decides whether you left. Its list of what counts is long, weighted toward daily life, and includes your family. Its burden of proof sits on you. And in every state named here, if you never file, the clock on the years you didn’t file never starts.
Who this is and isn’t for
The mail-and-hope plan works fine for a lot of people, and I’d rather say so than scare anyone. If you left a state with no income tax, there’s no former state waiting to tax you as a resident, and most of this doesn’t apply to you. If your income is modest and your old state is asleep, the odds are with you. If you left a state that doesn’t audit, you’ll probably never hear from it.
It’s for the person with real money, an old state with an income tax, and ties they didn’t cut: the house they kept “for the summers,” the spouse who stayed for a school year, the business that’s still there, the doctor they still fly back to see. That person has done half of a two-step, and the state that writes the rules for the second half has a few years from the day they file, or forever if they don’t.
One more thing, since you’re reading a website written by a man who has spent eleven years in hotels. Everything a nomad publishes is potential evidence. In my case it all points the same direction; nothing I’ve written in eleven years puts me in a North Carolina home, because there isn’t one. The nomad who moved his domicile to South Dakota in March and spends July posting from the lake house he kept in Minnesota is writing the auditor’s exhibit list himself, one photo at a time.